Latest
What You Have to Decide Before Anybody WritesWriting It Before You Need ItCross Training Covered Everything Except the Role That Mattered MostBehind the Book: You Don’t Own Anything AnymoreBehind the Book: The Woke VirusBehind the Book: Galactic InvasionWhat’s New at The Writing King: Week of November 8, 2026Alexander Zhidkov: Decision MakingJessi Szurek: Expand Your RangeYou Don’t Own Anything AnymoreThe Budget Decided How My Department Was ShapedWhy Your Competitor’s Book Is Working and Yours Would NotWhy Are These Guys Smiling? A Business Book That Became a Wrestling MemoirPangram Wants to Decide Who Gets PublishedWhat You Have Enough Material For Right NowWhen a Book Is the Wrong ToolThe Woke VirusGalactic InvasionChatGPT Turns Four: From a Free Research Preview to GPT-6What’s New at The Writing King: Week of November 1, 2026Diwali: The Festival of Lights and the Story Behind the LampsHow Much Water and Power Does Heavy AI Use Take? I Ran My Own NumbersBad Boys: Ride or Die (2024)Vesuvius Day: The Teenager Who Wrote Down Pompeii’s Last DayAnti-Communism Week: Remembering the Writers Communism SilencedVoyager 1 One Light-Day: Fifty Years to Travel One Day of LightVellum Added an Optional AI Feature. A Pile-On Killed It in a Day.Are AI Subscriptions Losing Money? The Gym Membership Math Says NoAI Terms Every Writer Should Know, and Why Each One MattersWorking While Sick: What 24/7 On Call Cost MeHe Banned AI From His Writing Group. His Own Cover Got Called AI Slop.Who Writes the Fake Fan Mail Authors Get? Inside the Scam CompoundsSMS Appointment RemindersJoe Rockey: Ghostwriting His BookDarrell Stern: Stop Being Invisible, Become UnmissableFree BooksHow to Turn Your Expertise Into a Book People Want to Read | The Expert MethodWhat’s New at The Writing King: Week of October 25, 2026Challenger Remembrance Day: The Engineer Who Wouldn’t SignJoel Salomon: The Truth About MoneyReddit Is Putting Up a Login Wall. Wikipedia Won’t Be Far Behind.Victoria Chemko: The Body Is the First TechnologySir Patrick Stewart: A TributeA Year in the Bank: ADHD, Face Blindness and the Freedom to Walk Out | The Impossible Puzzles Show, Episode 326A Yale Economist Says We Won’t Be Missed. He Forgot the Bread Line.Walter Koenig: A TributeAI Has Paid Off Outside Tech. Apollo Is Reading the Wrong Scoreboard.I Don’t Post Bad ARC Reviews. I Send the Author a Note.The Little Red Book of Stuff That Works!Your Kids Are Your Own Fault
The Writing King Your Ethical Ghostwriter. Your Story, Done Right.

The Same Private Equity Playbook, One Industry After Another

TL;DR: I never set out to write about the decline of American business. After twenty years managing technology at Trader Joe’s and a decade listening to executives tell me their real stories, I kept seeing the same private equity playbook destroying one industry after another. I’m tired of pretending that widespread business degradation is just how markets work.

I never set out to write a book about the decline of American business. I was perfectly happy ghostwriting memoirs and helping executives tell their success stories. But after twenty years managing technology at Trader Joe’s and then a decade listening to business leaders share their real stories, I started noticing patterns that kept me awake at night.

The same private equity playbook destroying one industry after another. The same optimization algorithms that could improve customer service getting repurposed to extract from it. The same executives who built great businesses explaining how they were pressured to dismantle what made those businesses great.

What does the private equity playbook look like from inside?

Ordinary, and that makes it difficult to argue with while it’s happening.

Nobody in these rooms describes themselves as degrading a business. They describe a margin target, a cost line that’s grown, a service level that’s above what the market requires. Each decision is defensible on its own terms and most of them are individually correct. What accumulates is a company that’s worse at the thing it exists to do, arrived at by a series of decisions where nobody chose that outcome. I watched companies I’d shopped at my whole life turn into hollow shells of themselves. Airlines that once made flying feel special now treat passengers like cattle. Department stores that anchored communities became something else.

Is criticism of private equity only nostalgia?

It’s a fair challenge and the answer is that the changes are measurable.

Everybody thinks things were better when they were younger and most of the time everybody is wrong. So the test has to be specific instead of atmospheric. Seat pitch. Fee structures. Staffing per store. Product lifespan. Time to reach a human being.

Those are numbers instead of feelings, and where I could find them they moved in one direction. That doesn’t make every memory accurate. It does mean the general impression is tracking something real.

Why do executives go along with a private equity playbook?

Why executives go along with a playbook they disagree withThe pressure is structural. The people describing these decisions were not villains, they were people who had built something they were proud of, explaining how they were pressured to take it apart, usually with some regret and usually with a clear account of what the alternative would have cost them personally. An executive who refuses is replaced by one who does not. That is not an excuse and it is an accurate description of the mechanism. Blaming people is emotionally satisfying and analytically useless, because the same structure produces the same result with different people in the chairs.Why they go along with itBlaming people is satisfying and useless. The structure does not need them.1They built somethingAnd were proud of it2The pressure arrivesTo take it apart, on a scheduleset somewhere else3Refusal has a priceWhich they can describe precisely,because they calculated it4The chair gets refilledAn executive who refuses is replacedby one who does notThe same structure produces the same result with different people in the chairs.
Why executives go along with a playbook they disagree withThe pressure is structural. The people describing these decisions were not villains, they were people who had built something they were proud of, explaining how they were pressured to take it apart, usually with some regret and usually with a clear account of what the alternative would have cost them personally. An executive who refuses is replaced by one who does not. That is not an excuse and it is an accurate description of the mechanism. Blaming people is emotionally satisfying and analytically useless, because the same structure produces the same result with different people in the chairs.Why they go along with itBlaming people is satisfying and useless. Thestructure does not need them.1They built somethingAnd were proud of it2The pressure arrivesTo take it apart, on a scheduleset somewhere else3Refusal has a priceWhich they can describe precisely,because they calculated it4The chair gets refilledAn executive who refuses is replacedby one who does notThe same structure produces the same result withdifferent people in the chairs.

Because the pressure is structural, and I say that having listened to a lot of them describe it. The people telling me these stories had built something they were proud of. They explained how they were pressured to take it apart, usually with some regret and usually with a clear account of what the alternative would have cost them personally. An executive who refuses is replaced by one who doesn’t. It excuses nobody, and it’s an accurate description of the mechanism. Blaming people is emotionally satisfying and analytically useless, because the same structure produces the same result with different people in the chairs.

Is private equity rollup just how markets work?

No, and that phrase is doing an enormous amount of concealing. I wrote this book because pretending that widespread business degradation is just how markets work is a cop-out. It’s not. It’s how these particular markets work, structured by these particular incentives. The proof is that the exceptions exist. There are companies that haven’t done this, and they’re not outliers or lucky accidents. They’re companies that made different choices about ownership, about optimization, and about what success means.

Blaming people is emotionally satisfying and analytically useless, because the same structure produces the same result with different people in the chairs.

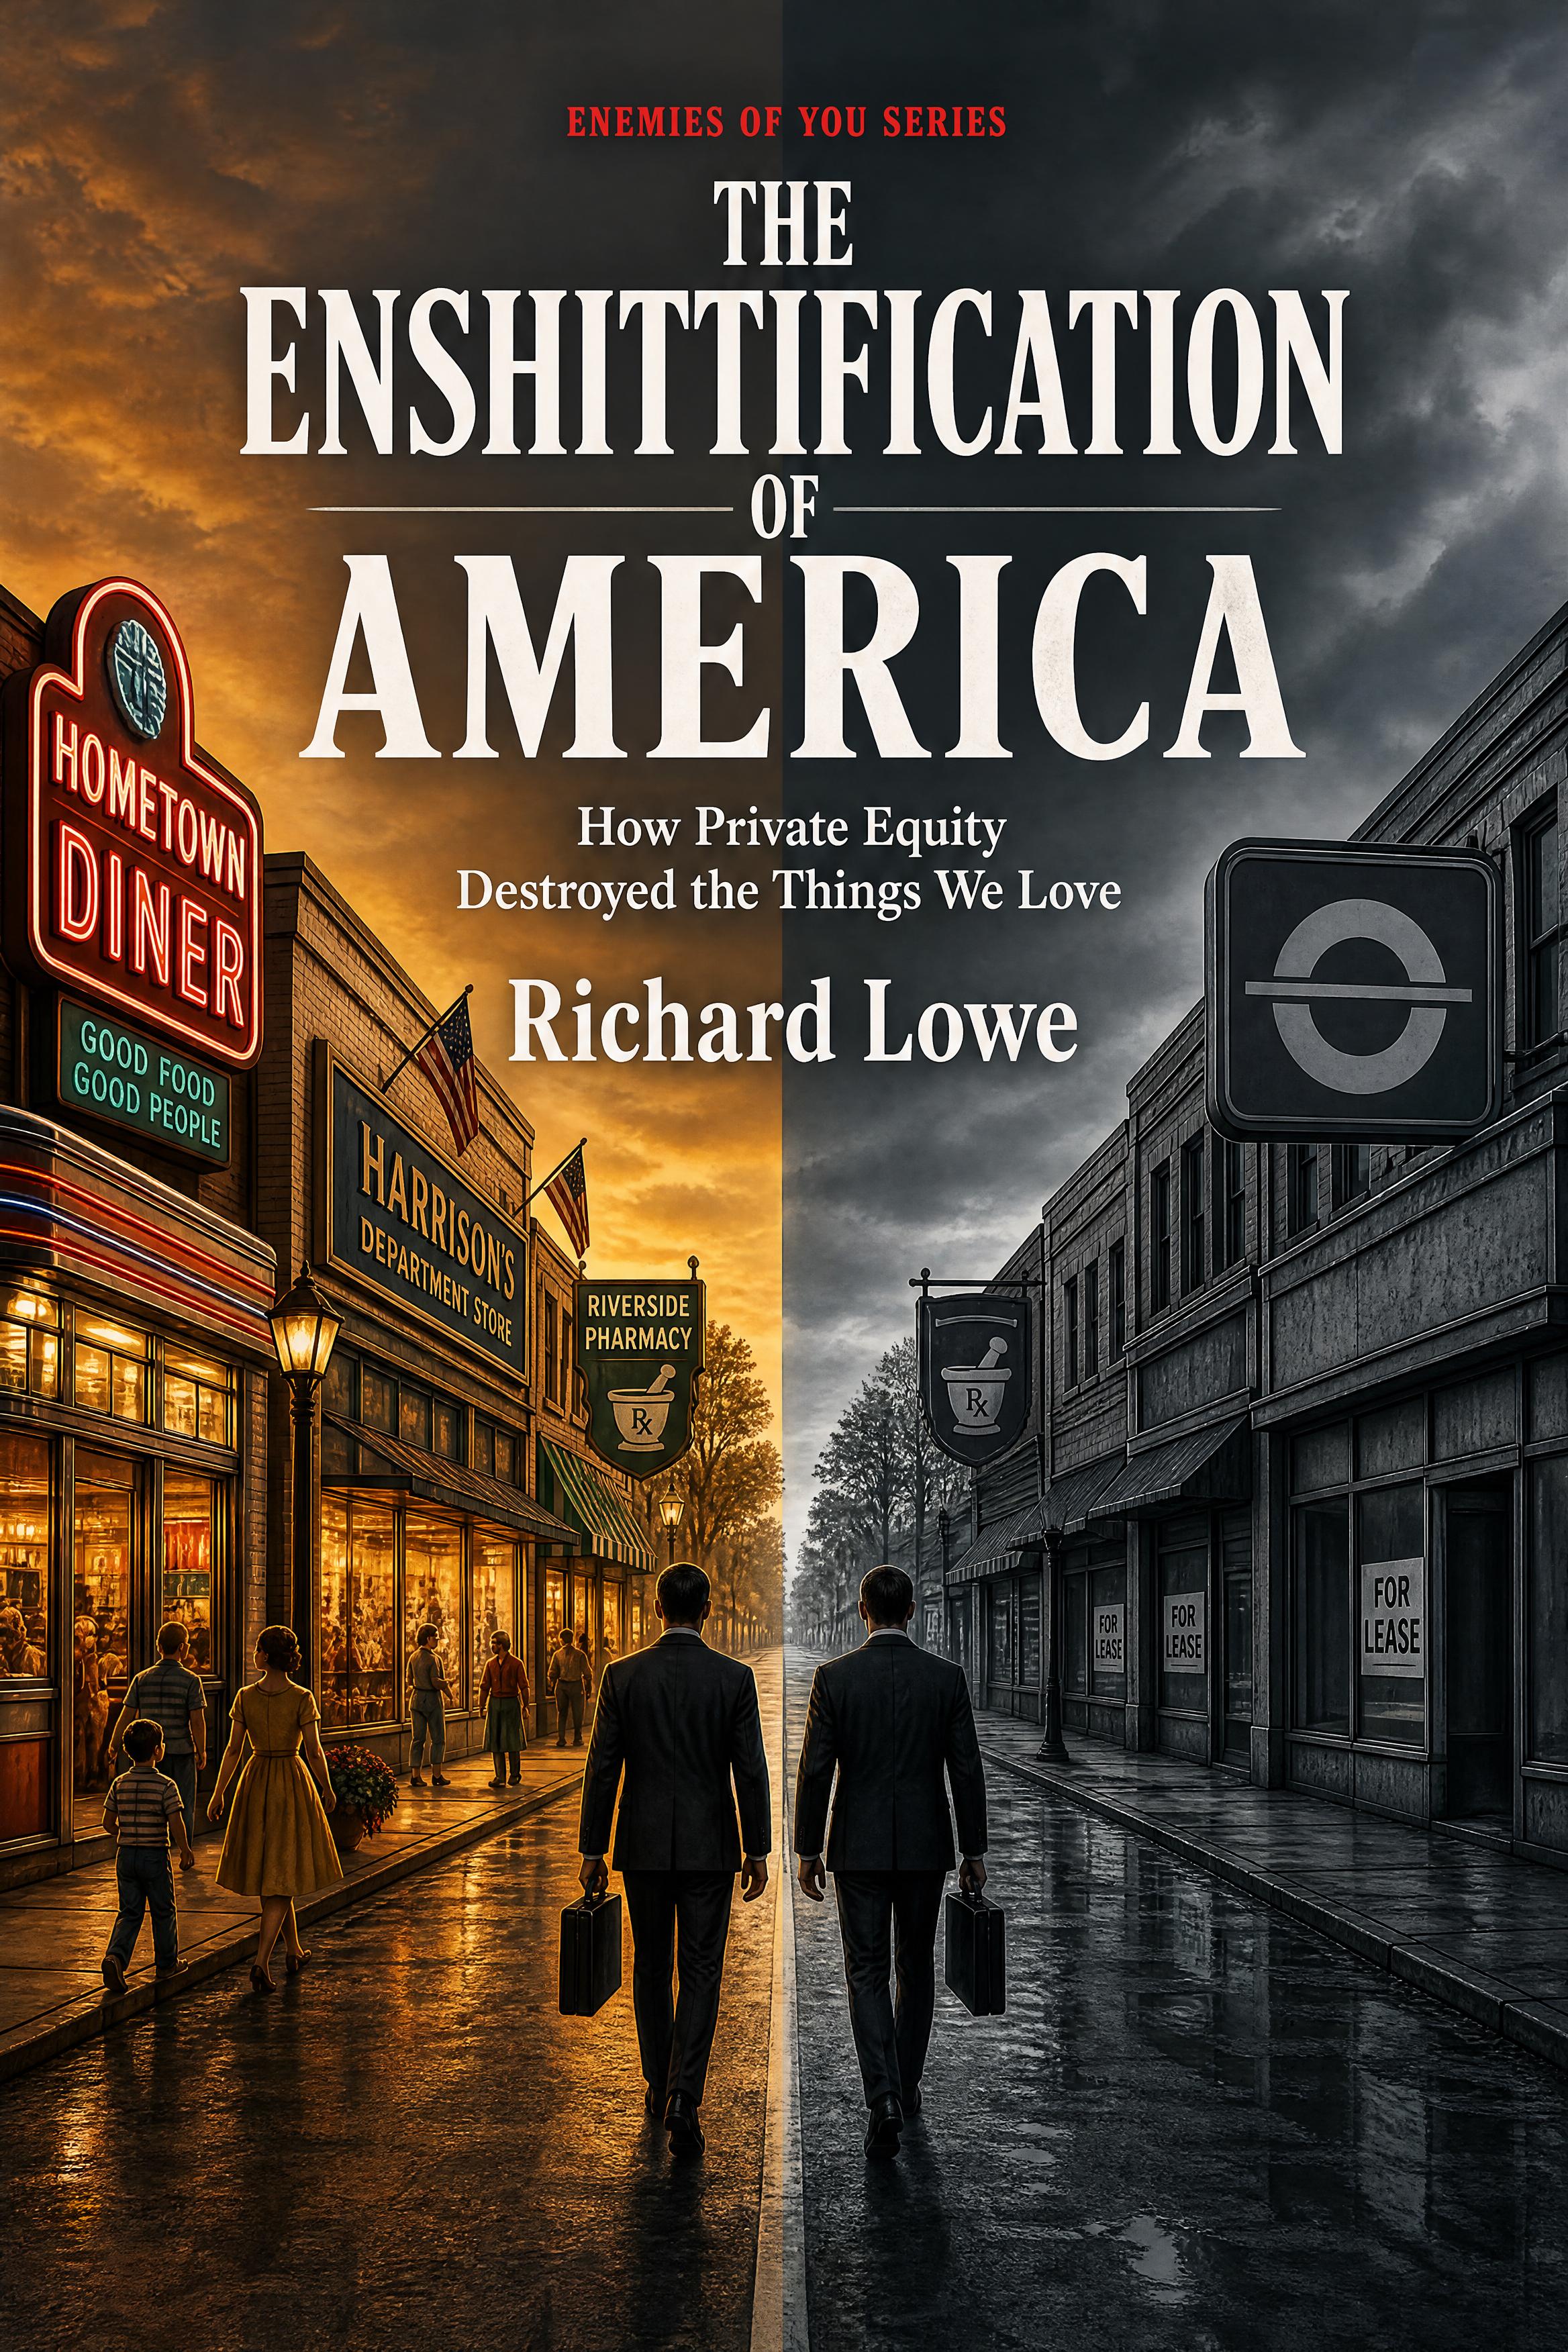
If the outcome were a law of markets, there would be no exceptions. There are. That means it’s a choice. That means somebody chose. Get stars in your eyes and go after public or private equity. That’ll burn a company down. The financial stress will kill you. I wrote a whole book on it, The Enshittification of America.

Why does the technology part of the private equity playbook matter?

Because I spent twenty years on that side of it and watched the same tools go both ways.

The optimization algorithms that could improve customer service are the same ones that get repurposed to extract from it. It’s the same technology. What differs is the objective it’s pointed at, and that objective is set by people who are usually several layers away from anybody who will experience the result. I couldn’t have written that part without the technical background, and it’s why the book isn’t simply an economics argument.

Common defenses of the playbook and the book’s answers
Common claim The book’s answer
It is only nostalgia The changes are measurable: seat pitch, staffing per store, product lifespan, time to reach a human
Executives are the villains The pressure is structural; a refusing executive is replaced by one who complies
It is just how markets work Exceptions exist, so it is a choice made under particular incentives
The technology is to blame The same tools can improve service or extract from it; the objective decides
Each decision was reasonable Individually defensible decisions accumulate into a worse company

The book on this: The Enshittification of America is the pattern traced across industry after industry, from twenty years inside a large company and a decade listening to executives describe what they were pressured to dismantle.

My take

Private equity’s damage is a choice, and the companies that chose differently prove it. The same optimization tools that could improve customer service get pointed at squeezing it. The objective decides the outcome, and the people setting it never see the result. Think hard before you chase public or private equity money for your own company. The financial stress will burn it down.

What is the argument against the private equity playbook?

The degradation is a pattern. It repeats across industries with the same steps.

It’s produced by incentives instead of by villains. That’s worse, because incentives don’t change their minds.

The exceptions prove it’s a choice. Different ownership structures produce different behavior.

The same tools can do either. The technology is neutral and the objective function isn’t.

Saying it’s just how markets work is a way of ending the conversation. It’s a refusal to give an explanation.

I would have been content to keep writing memoirs. What changed is that I heard the same story often enough, from people who had been in the room, that not writing it down started to feel like a choice of its own.
From the author
The Enshittification of America by Richard Lowe

The Enshittification of America
Private equity runs the same playbook in industry after industry. The Enshittification of America examines thirteen industries and how good businesses were taken apart.
Frequently Asked Questions

What is the private equity playbook?
Acquire, load with debt, cut the things customers can’t see immediately, extract fees, and exit before the damage shows in the numbers. It’s repeatable, it’s legal, and it works reliably enough to be applied to one industry after another.
Is private equity rollup just how markets work?
No, and that phrase is doing a lot of concealing. It’s how these particular markets work, structured by these particular incentives. Different ownership structures produce different behavior, and that’s the evidence that the outcome is a choice.
Why do executives go along with private equity cost cutting?
Because the pressure is structural and their alternatives are limited. The ones I’ve listened to were explaining how they were pressured to dismantle what had made their businesses good, and describing it with some regret.
Which companies avoid the private equity playbook?
The ones that made different choices about ownership, about what to optimize, and about what success means. They’re not outliers or lucky accidents. That matters, because it shows the pattern isn’t inevitable.
Why does it feel like everything is getting worse?
Because in a lot of specific, measurable ways the things you buy and the services you use are worse than they were, and you’re not imagining it. The airlines, the department stores, the products that used to last are the evidence.

About the Author
Richard Lowe, professional ghostwriter

Richard Lowe is a professional ghostwriter and author with 113+ books authored and 54+ ghostwritten. Before writing full time he spent 33 years in enterprise technology, including 20 years as Director of Computer Operations and Technical Services at Trader Joe's. He writes nonfiction, fiction and memoir, and works with executives and experts on books that build authority.

More about Richard Lowe →

Disclaimer

The views and opinions expressed in this blog post are solely those of Richard Lowe and are based on personal experience and research. This content is for informational purposes only and should not be construed as professional legal, financial, accounting, or business advice. Always consult with qualified professionals before making important business or legal decisions. Richard Lowe is not a lawyer, accountant, or licensed professional advisor, and this content does not establish any professional relationship.

0 comments

No comments yet. Yours can be the first.

Was this useful?

Leave a comment